Rat-infested property is “suitable for use as a dwelling”
The First-tier Tribunal has found that a property in disrepair, inhabited by rodents, is still suitable for use as a dwelling for tax purposes. This sounds illogical - so what’s the full story?
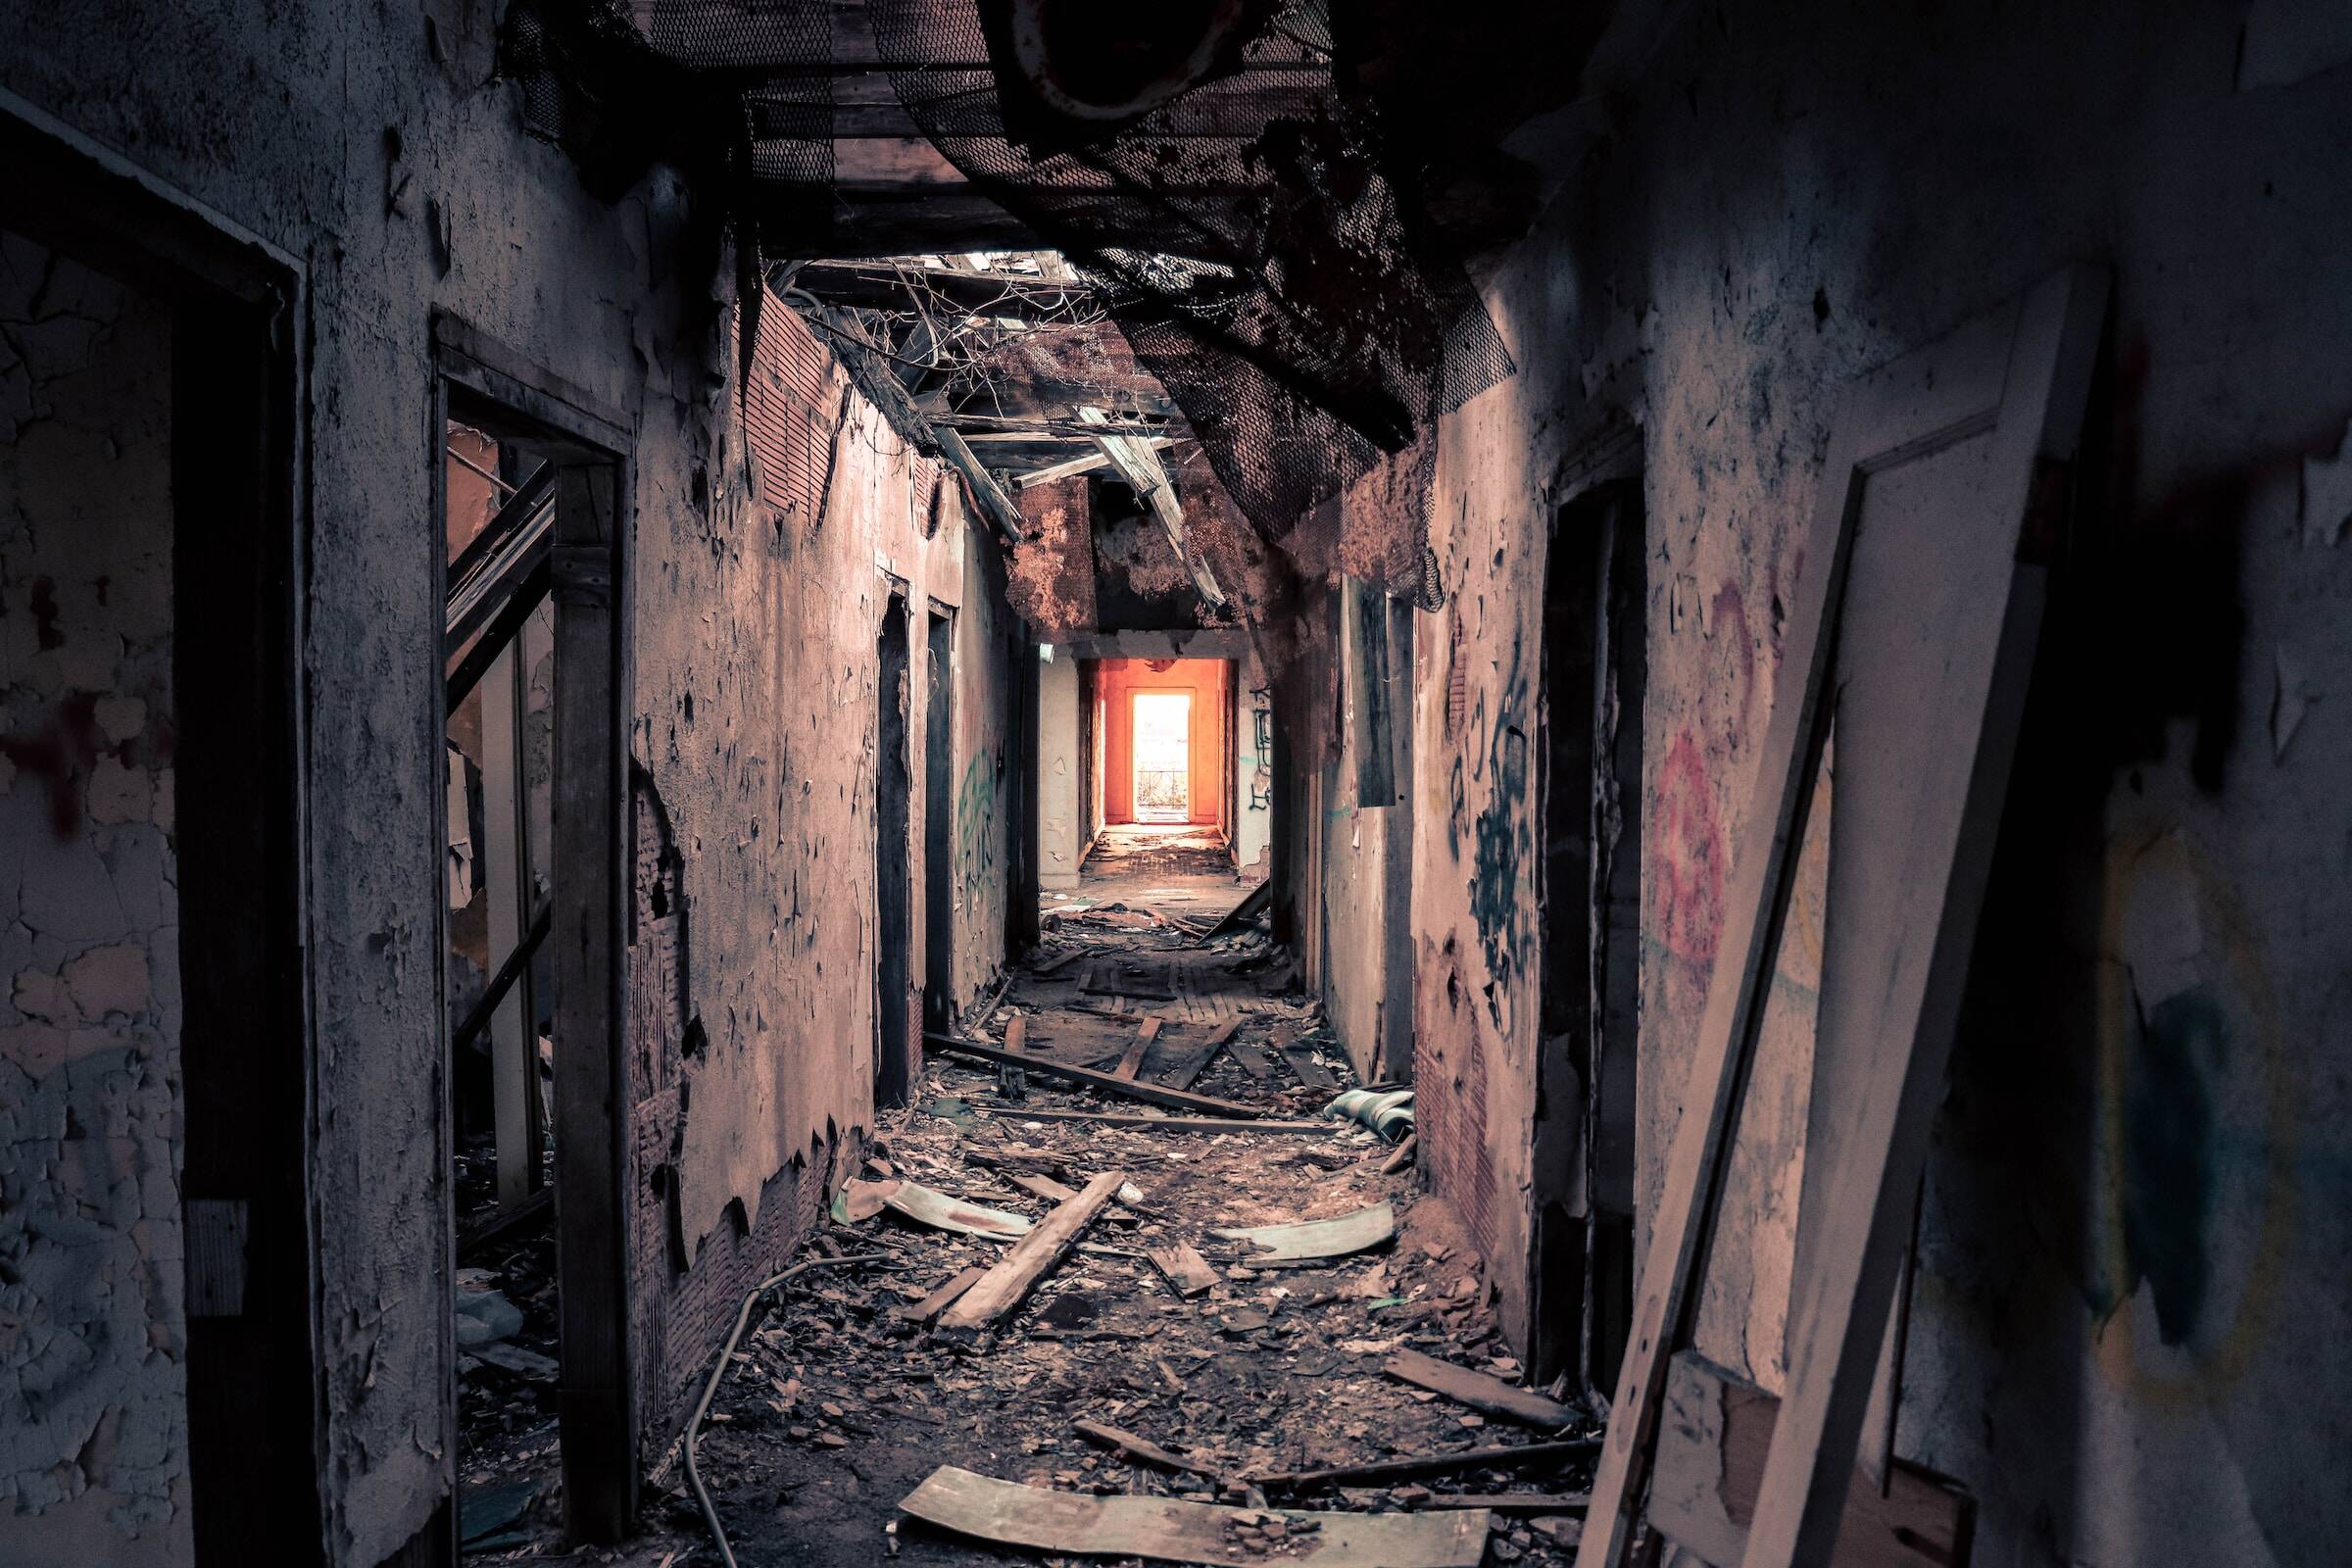
In Mudan & Anor v HMRC the taxpayers (the Ms) purchased a £1.7m property in London that had been empty for five months after the previous tenants were evicted. During that time, the property had been broken into and vandalised, none of the utilities worked and mice and rat droppings covered the kitchen. The boiler had been ripped off the wall, the gas, electricity and water were not functioning safely and rainwater was leaking into the property. It took nine months of renovations before the Ms moved into the property.
Higher rates of stamp duty land tax (SDLT) are chargeable on residential properties, with the pertinent part of the definition being that the property is residential if it is “suitable for use as a dwelling”. Due to the state of the property, the Ms argued that it was not suitable to be occupied and so lower rates of SDLT should apply. HMRC, and ultimately, the tribunal disagreed. The judge confirmed that the bar for a property not to be suitable for use as a dwelling was set very high, and that a building which was recently used as a dwelling, has not in the interim been adapted for another use, and is capable of being so used again will count as a dwelling for SDLT purposes. An additional £100,000 SDLT was due on the purchase, and the appeal was dismissed.
Related Topics
-
Do dividend waivers still work?
You need to take a dividend from your company but there’s just one problem. Your business partner, who is also a 50% shareholder, doesn’t want to take any more income from the company during this tax year. What’s the solution?
-
Save tax by combining directors’ loan accounts
You started a company last year and it’s time to prepare its first accounts. Your director’s loan account (DLA) is in credit but your spouse’s is overdrawn. Might amalgamating the DLAs avoid or reduce a tax charge?
-
Updated guidance on mandatory payrolling of benefits in kind
Much like the rollout of mandatory payrolling of benefits in kind, HMRC guidance on the matter is coming in dribs and drabs. What's the latest?